The 2025 German Tax Return for Employees: A Step-by-Step Guide
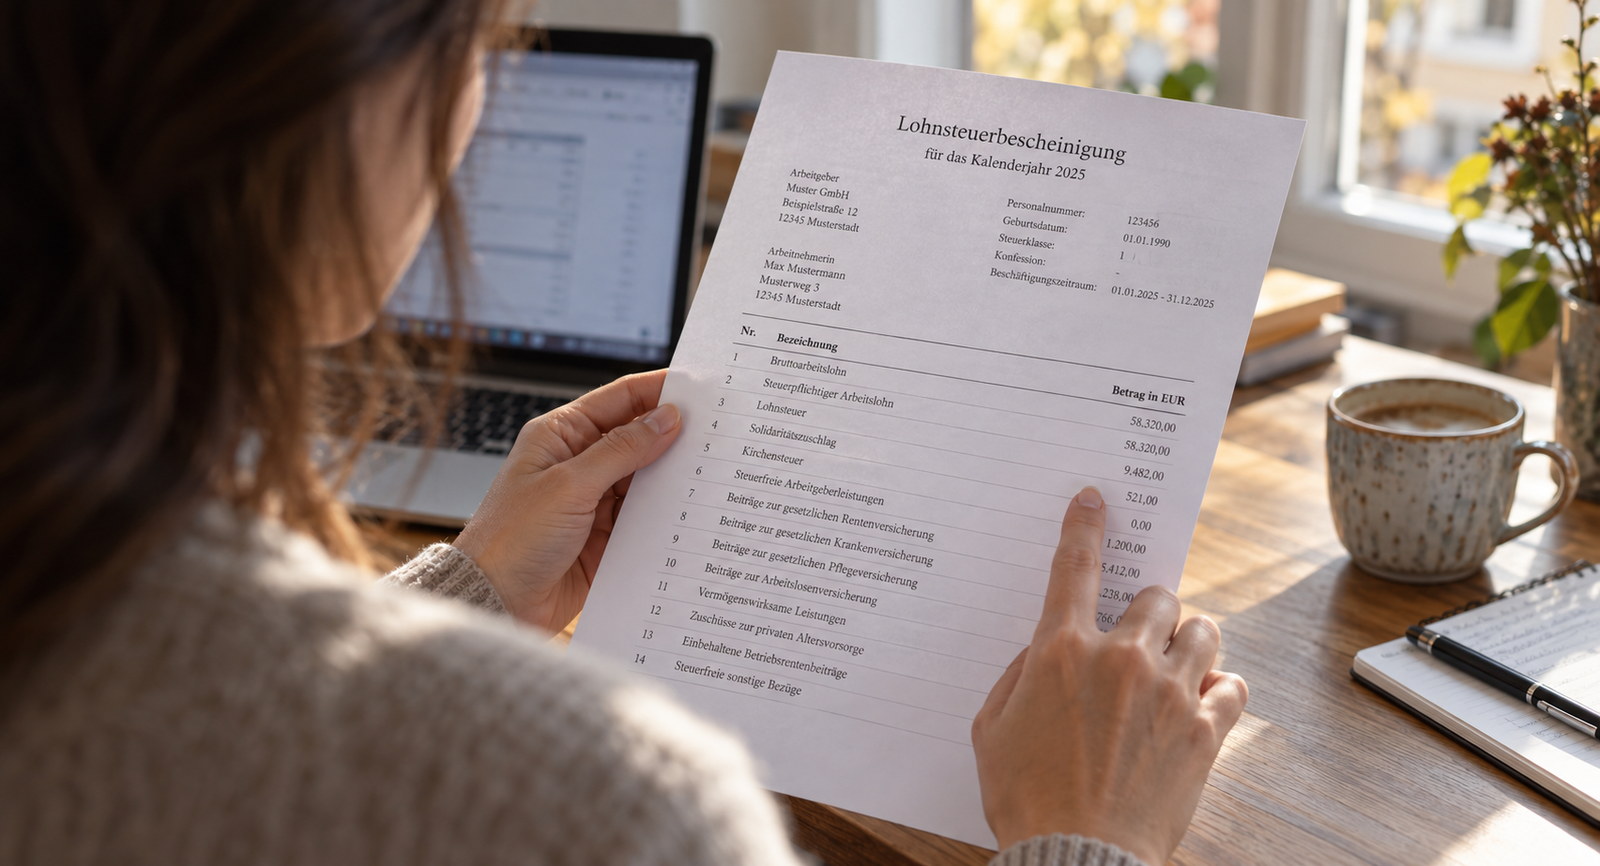
For a lot of employees in Germany, the 2025 Einkommensteuererklärung (income tax return) is the first one they do themselves. It is less work than the subject’s reputation suggests: most of what you need sits on a single document, the Lohnsteuerbescheinigung (annual payroll tax statement), and the rest is a handful of amounts you already know.
This guide covers tax year 2025, the return you file in 2026, and works through it in the order you actually do it.
The short version
- For mandatory filers, the 2025 deadline was 31 July 2026. With a Steuerberater (tax adviser) or a Lohnsteuerhilfeverein (wage tax assistance association), it runs to 1 March 2027.
- If you were not required to file, you can still submit your 2025 return voluntarily until 31 December 2029.
- The Grundfreibetrag (basic tax-free allowance) for 2025 is 12,096 euros. No income tax is due below that.
- Most employees need the main form, Anlage N and Anlage Vorsorgeaufwand. Everything else depends on your situation.
- You do not submit receipts. You have to be able to produce them if asked.
- Filing is electronic. You do not necessarily need your own ELSTER certificate if you file through a provider.
Do you actually have to file?
There are two routes into a German tax return, and their deadlines are completely different.
Pflichtveranlagung (mandatory assessment) means the tax office expects your return. That applies, among other cases, if:
- You received wage replacement benefits over 410 euros, such as short-time work allowance, unemployment benefit or parental allowance
- You had wages from more than one employer at the same time, so tax class VI was involved
- You are married and used the III and V combination or the Faktorverfahren
- You had an allowance registered as a wage tax deduction feature
- You had secondary income over 410 euros, for instance from self-employment or letting property
- You received a severance payment taxed at the reduced rate
Antragsveranlagung (assessment on application) means you file voluntarily. It tends to pay off if you had high work-related expenses, worked only part of the year, got married, or carried significant medical costs.
The practical difference is the deadline. Mandatory filers had until the end of July. Voluntary filers have four years from the end of the tax year.
The 2025 deadlines
| Case | Deadline |
|---|---|
| Mandatory, filing yourself | 31 July 2026 |
| Mandatory, with a tax adviser or Lohnsteuerhilfeverein | 1 March 2027 |
| Voluntary | 31 December 2029 |
1 March 2027 arises because the statutory date at the end of February falls on a Sunday, so the deadline moves to the next working day.
If you were required to file and the July deadline has passed, file anyway. The tax office can impose a Verspätungszuschlag (late filing penalty), and its size depends partly on how long it takes for the return to arrive.
Which forms you need
The return consists of a main form plus schedules. You complete only the ones that apply.
| Form | Covers |
|---|---|
| Main form ESt 1 A | Personal details, religious affiliation, bank details |
| Anlage N | Employment income and work-related expenses |
| Anlage Vorsorgeaufwand | Pension, health, long-term care and unemployment insurance |
| Anlage Sonderausgaben | Donations, church tax, certain education costs |
| Anlage Außergewöhnliche Belastungen | Medical costs, care, disability, maintenance |
| Anlage Kind | One per child, for allowances and childcare costs |
| Anlage S and Anlage EÜR | Only for self-employed secondary income |
| Anlage KAP | Investment income where too little or too much tax was withheld |
For an employee with no children and no side income, it comes to three forms in practice: main form, Anlage N, Anlage Vorsorgeaufwand.
What to gather first
Have the following ready before you start. With complete paperwork, a straightforward return takes under an hour.
- Lohnsteuerbescheinigung for 2025, one from each employer
- Steueridentifikationsnummer, eleven digits, on the statement and on every tax assessment
- IBAN of the account the refund should go to
- Certificates for wage replacement benefits from the employment agency, health insurer or parental allowance office
- Proof of insurance contributions not already on the payroll statement, such as private liability, occupational disability, Riester or Rürup
- Receipts for work-related expenses: training, equipment, job applications, professional body fees
- Distance and working days: kilometres to work, and how many days you spent in the office and at home
- Invoices for tradespeople and household services, each with a bank statement, since cash payment is not accepted
- Donation receipts
- Medical cost receipts, if significant amounts accumulated
If this is your first time holding a Lohnsteuerbescheinigung and you are not sure which number means what, our guide to reading your Lohnsteuerbescheinigung goes through it field by field.
Working through the return
1. Personal details and assessment type
Name, address, tax ID, religious affiliation, bank details. Married couples choose here between joint and separate assessment. Joint assessment is better in most cases because of the splitting tariff, particularly where incomes differ.
2. Carry across your employment income
Gross pay, wage tax withheld, solidarity surcharge, church tax. With more than one employer, each statement is recorded separately rather than added together.
3. Enter work-related expenses
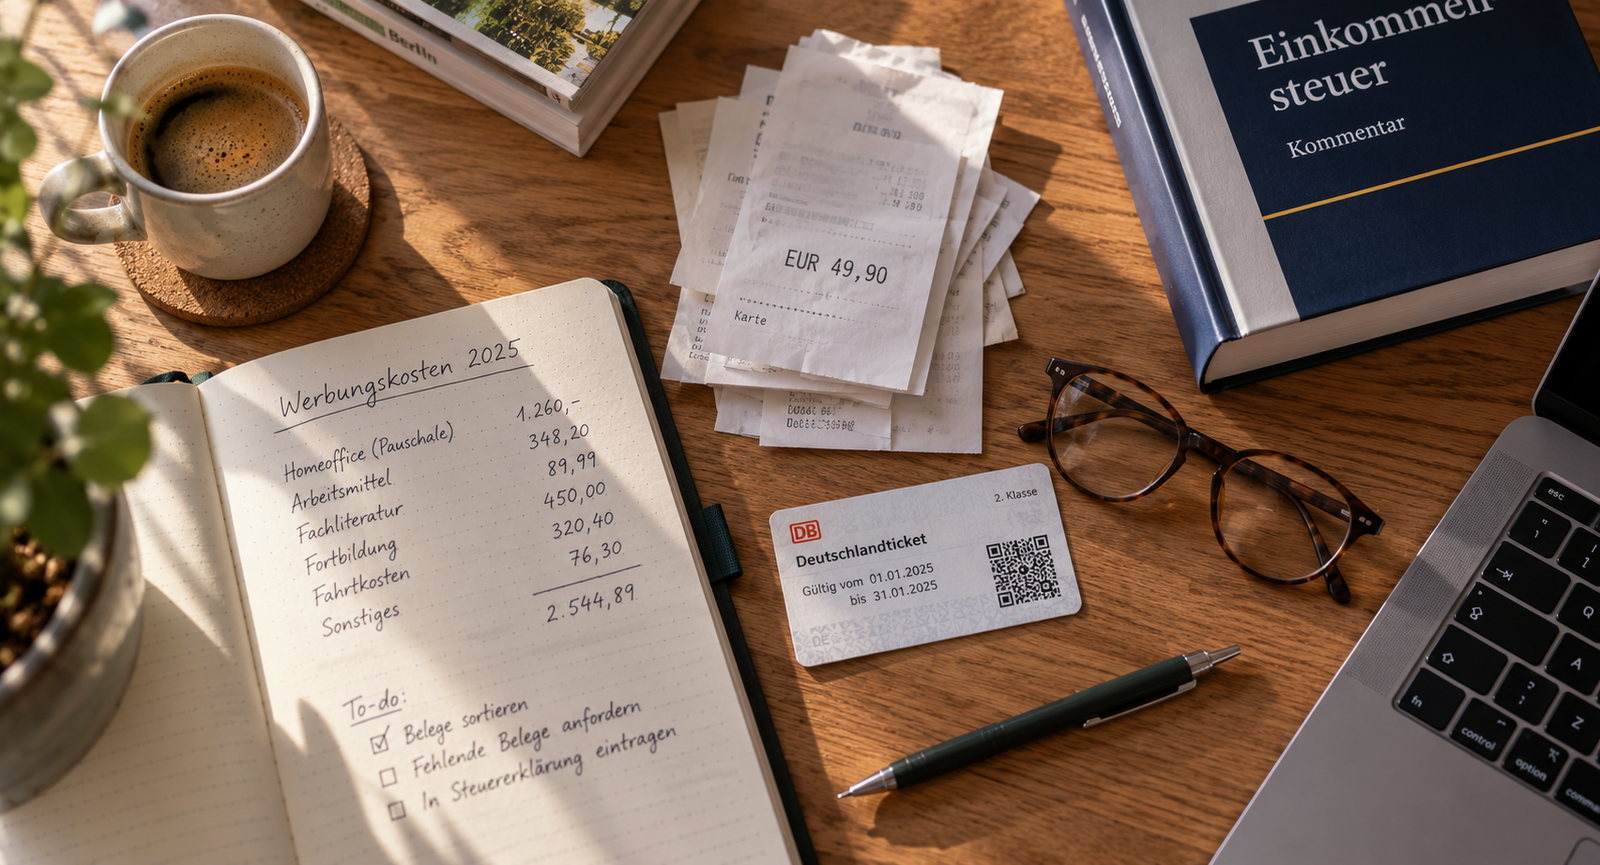
Start with the commute, since it is usually the largest item. For 2025 the rates are 0.30 euros per kilometre for the first 20 kilometres and 0.38 euros from kilometre 21, one way, per working day. Then home office days at 6 euros a day, work equipment, training, job applications and membership fees.
Keep in mind that the tax office deducts the 1,230 euro Arbeitnehmer-Pauschbetrag regardless. Only what exceeds it produces an additional refund. Our guide to work-related expenses for employees sets out which items get you there.
4. Record insurance contributions
The block from your payroll statement covering pension, health, long-term care and unemployment insurance, plus private policies providing basic cover. For 2025, retirement provision contributions count up to 27,566 euros for single assessment and 55,132 euros for joint assessment.
5. Special expenses and extraordinary burdens
Donations, church tax paid, childcare costs. For childcare, 80 percent of the expenses are deductible, up to 4,800 euros per child per year.
Medical costs, care costs and similar burdens only have an effect once they exceed your zumutbare Belastung (reasonable burden), which is calculated in bands according to income, marital status and number of children. Collecting receipts therefore pays off mainly in years with heavy spending.
6. Tradespeople and household services
These are not deducted from income. They come straight off the tax due. You need an invoice and payment by bank transfer. Material costs do not count, only the labour element.
7. Check and submit
Before submitting, reconcile the figures against your payroll statement and check that the certified period covers the whole year. Then file electronically.
Key figures for 2025
| Item | 2025 |
|---|---|
| Basic tax-free allowance | 12,096 euros |
| Employee standard allowance | 1,230 euros |
| Commuting allowance, kilometres 1 to 20 | 0.30 euros |
| Commuting allowance, from kilometre 21 | 0.38 euros |
| Home office day rate, capped at 1,260 euros | 6.00 euros |
| Child allowance including care allowance, joint | 9,600 euros |
| Kindergeld per child per month | 255 euros |
| Relief amount for single parents | 4,260 euros |
| Childcare costs, 80 percent, maximum per child | 4,800 euros |
For comparison with next year’s return: from tax year 2026 the basic allowance rises to 12,348 euros, Kindergeld to 259 euros a month, and the commuting allowance becomes a flat 0.38 euros from the first kilometre.
What happens after you submit
The tax office reviews the return and issues a Steuerbescheid (tax assessment). How long that takes depends on the federal state and the office’s workload; electronically filed returns are generally processed faster than paper ones.
When the assessment arrives, compare it with your return. The tax office explains any differences in the notes at the end. If you disagree, you have one month to file an objection, counted from when the assessment is deemed served.
How Solobooks helps
Solobooks takes you through the return in the order described above, as questions rather than form fields. Your estimated refund is recalculated as you go and stays visible throughout, so you can see which entry moves the number and which does not.
For tax year 2025 it covers the main form, Anlage N, Anlage Vorsorgeaufwand and the schedules for children and extraordinary burdens. If you are self-employed on the side, that part runs through Anlage S and Anlage EÜR.
Before submission Solobooks checks for incomplete entries and blocks filing while anything is missing. Filing goes electronically through ELSTER without you uploading a certificate of your own. You pay once, on submission, with no subscription.
The tax return page has more on scope and process. If you are self-employed as your main activity, bookkeeping is the better starting point, and our guide to income-expense accounting explains the profit calculation behind it.
Frequently asked questions
Is filing worth it at all? For most employees, yes, because wage tax withheld over the year takes no account of your individual deductions. If your work-related expenses exceed 1,230 euros, or you only worked part of the year, a refund is likely.
I missed the 31 July 2026 deadline. What now? File promptly. In mandatory cases a late filing penalty can apply, and its size depends partly on how late the return is. For voluntary filing the date does not matter; that deadline runs to the end of 2029.
Can I still file for earlier years? Voluntary filing is subject to the four-year rule. For 2022 it ends on 31 December 2026.
Do I need an ELSTER certificate? For Mein ELSTER, yes. If you file through a provider, the provider handles transmission and you do not need your own certificate.
Will my data be pre-filled automatically? That requires you to register with Mein ELSTER under your own tax ID and give consent there. With Solobooks you enter the figures from your payroll statement yourself.
Joint or separate assessment? Where incomes differ, joint assessment is almost always better. Separate assessment can help if one spouse received wage replacement benefits subject to Progressionsvorbehalt, or is claiming large extraordinary burdens.
How long do I keep receipts? Until the assessment is final, meaning the objection period has expired and no queries are outstanding. A year after receiving the assessment is enough in practice.
Sources
- § 25 EStG, assessment to income tax
- § 46 EStG, assessment where income from employment is received
- § 149 AO, filing of tax returns, and § 108 AO on calculating deadlines
- § 152 AO, late filing penalty
- § 355 AO, objection period
- Finanzministerium Rheinland-Pfalz, table of tax return filing deadlines
- Bundesfinanzministerium, Die wichtigsten steuerlichen Änderungen 2026
Last checked: 17 September 2026. This article is general information, not tax advice for your individual case. Legislation and official guidance change, the current version of each source prevails.
Last updated: September 17, 2026
Expert Tip
If you were not required to file, you have until 31 December 2029 to submit your 2025 return. The July deadline only applies to mandatory cases.
— Solobooks Team