Home Office Deductions for Employees in Germany: Day Rate or Study
Since 2023 there have been two separate routes for working at home in the German tax system: the 6 euro Tagespauschale (day rate) and the deduction for a häusliches Arbeitszimmer (home study). They do not strictly exclude each other, but the conditions are completely different, and for most employees only one of them is realistic.
This guide covers tax year 2025, the return you file in 2026. What changes from 2026 is further down.
The short version
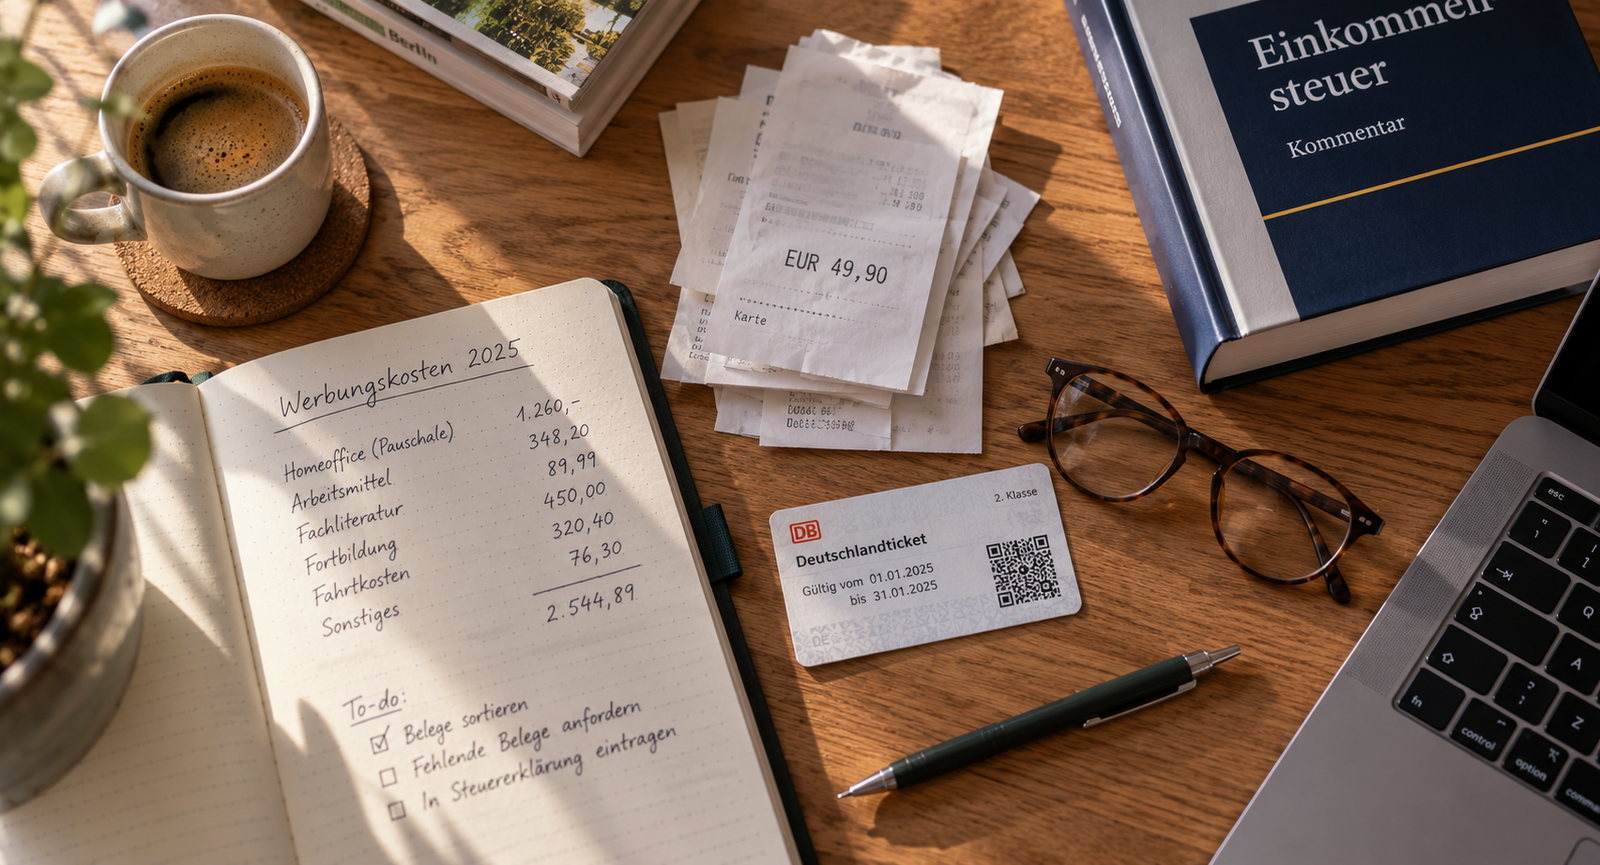
- The day rate is 6 euros for each day you worked predominantly at home, capped at 1,260 euros a year, which is 210 days.
- It is a work-related expense, so it counts towards the 1,230 euro Arbeitnehmer-Pauschbetrag (employee standard allowance), not on top of it.
- You cannot also claim the commuting allowance for the same day, unless no other workplace is permanently available to you.
- The home study requires that the room is the centre of your entire professional activity. If it is, you choose between actual costs and a flat 1,260 euros a year.
- Work equipment such as a desk, chair or monitor is separate and always deductible on top.
- From 2026 the day rate stays at 6 euros, but the higher commuting allowance changes the arithmetic.
The day rate
6 euros for each calendar day on which you carried out your work predominantly in your home. Predominantly means more than half of that day’s working time.
The annual cap is 1,260 euros, which is 210 days. Working from home more often does not get you more.
You do not need a dedicated room. The kitchen table qualifies, the bedroom qualifies, a corner of the living room qualifies. That is the essential difference from the home study.
The same-day rule
On a day you claim the day rate, you normally cannot also claim the commuting allowance for travelling to work. A day is either a home day or an office day.
There is one important exception. If no other workplace is permanently available to you, for instance because your employer keeps no desk for you, you can claim the day rate even on days when you travelled to a client or into the office.
The point almost everyone misses
The day rate is itself a work-related expense. The tax office already deducts the 1,230 euro standard allowance from every employee’s salary with no receipts at all. The 6 euros a day do not come on top, they count towards it.
An example: 120 days at home, 100 days in the office with a 12 kilometre one-way commute.
| Item | Amount |
|---|---|
| Day rate 120 × 6 euros | 720.00 euros |
| Commuting allowance 100 × 12 km × 0.30 euros | 360.00 euros |
| Total | 1,080.00 euros |
| Standard allowance | 1,230.00 euros |
| Effect | none |
Despite 120 days at home, this produces nothing. One more item, say a 400 euro office chair, lifts the total to 1,480 euros and puts 250 euros above the allowance.
Which is why the day rate is never worth looking at on its own, only alongside all your other work-related expenses.
The home study
The second route is much narrower, but has no ceiling.
The requirement: centre of your activity
The study must be the centre of your entire business and professional activity. This is not about how many hours you spend where, but about where the substance of your work happens.
For employees that bar is high. If you have a desk at your employer’s premises and work there regularly, you will not normally clear it. Realistically the deduction is for fully remote employees whose employer provides no workplace at all.
What the room has to be
A separate, enclosed room used almost exclusively for work. Private use beyond roughly ten percent disqualifies it. The guest room with a desk in it does not qualify, and a corner of the living room certainly does not.
Two ways to calculate
If the requirement is met, you choose:
Actual costs, apportioned by floor area. That covers rent or building depreciation, service charges, electricity, heating, insurance and redecoration of the room.
Example: a 90 square metre flat with a 12 square metre study, so 13.3 percent. Annual rent, service charges and electricity together come to 17,700 euros.
13.3 percent of 17,700 euros = 2,354 euros
The annual flat rate of 1,260 euros with no itemisation. The simpler route when your apportioned costs are lower, or when you cannot assemble the paperwork.
You do not have to decide in advance. Work out both and take the higher figure.
Which route for whom
| Day rate | Home study | |
|---|---|---|
| Dedicated room required | no | yes, separate and almost exclusively for work |
| Must be the centre of your work | no | yes |
| Ceiling | 1,260 euros | 1,260 euros flat, or uncapped with itemisation |
| Evidence | a record of the days | floor plan, lease, service charge statements |
| Typical case | hybrid employees | fully remote, no employer workplace |
Work equipment is always on top
Whichever route you take, work equipment is deductible separately: desk, office chair, monitor, keyboard, desk lamp, professional books.
Up to 800 euros net, meaning 952 euros including VAT, you deduct the full amount in the year of purchase. For computer hardware, peripherals and software the tax administration has accepted a one-year useful life since 2021, so even an expensive laptop is fully deductible straight away.
Where you also use something privately, claim the work share. A monitor you use only for work counts at 100 percent; a laptop split evenly counts at 50 percent.
What changes from 2026
The day rate stays at 6 euros and 1,260 euros a year. Something else changed: the commuting allowance rises on 1 January 2026 to 0.38 euros from the first kilometre.
That moves the distance at which an office day is worth more than a home day:
| Office day beats home day from | |
|---|---|
| Tax year 2025 | 20 km |
| From tax year 2026 | 16 km |
No reason to work differently, but it explains why the same split produces a different result from 2026. More in our guide to the 2026 commuting allowance.
What to do
- Count your home days. A calendar entry is enough. The tax office expects plausible numbers, not 210 home days alongside 30 days of holiday and 100 office days.
- Track office days separately. The same day only gets one of the two.
- Check whether your employer provides a workplace. Only if it does not does the exception apply, and only then is the study route realistic.
- Keep receipts for equipment. You do not submit them, but you have to be able to produce them.
- Add it all up against 1,230 euros. Only above that is there any benefit.
How Solobooks helps
In Solobooks you enter the number of home office days and your commute details in the guided Anlage N section. Both feed the same calculation, so you can see whether your work-related expenses clear the 1,230 euro allowance or not.
Your estimated refund stays visible while you enter things, so you can add an item and see immediately whether it changes anything.
For the return end to end, see our step-by-step guide for employees.
Frequently asked questions
Do I get the 6 euros on top of the 1,230 euro allowance? No. The day rate is itself a work-related expense and counts towards the allowance.
Can I claim the home office day rate and the commuting allowance for the same day? As a rule, no. The exception applies where no other workplace is permanently available to you.
Does half a day at home count? Only if you worked predominantly at home that day, meaning more than half your working time.
Do I have to prove the days? You have to make them credible. A simple list or calendar is usually enough.
My study is not the centre of my work. What is left? The 6 euro day rate. A deduction for the room’s costs is not available.
I share the study with my partner. How is it calculated? If both of you meet the conditions, each can claim your share. The 1,260 euro annual flat rate is per person.
What about renting a coworking desk? That is not a home study. It is a separate work-related expense and fully deductible.
Sources
- § 4 Abs. 5 Satz 1 Nr. 6b EStG, home study
- § 4 Abs. 5 Satz 1 Nr. 6c EStG, day rate for working at home
- § 9 EStG, work-related expenses
- § 6 Abs. 2 EStG, low-value assets
- Bundesregierung, Steueränderungsgesetz 2025, approved by the Bundesrat on 19 December 2025
Last checked: 17 September 2026. This article is general information, not tax advice for your individual case. Legislation and official guidance change, the current version of each source prevails.
Last updated: September 17, 2026
Expert Tip
The day rate does not sit on top of the 1,230 euro standard allowance, it counts towards it. Someone who worked 100 days at home has 600 euros and still nothing.
— Solobooks Team