How to Register as a Freelancer in Germany: Step-by-Step Guide
Registering as a freelancer in Germany involves less paperwork than most people fear. At its core, it is one online form for the tax office. This guide covers what to settle first, which deadline applies, and what comes after you register.
Key points
- You tell the tax office (Finanzamt) that you have started within one month (§ 138(4) AO).
- You do this with the tax registration questionnaire (Fragebogen zur steuerlichen Erfassung), submitted electronically through ELSTER (§ 138(1b) AO). Paper is only allowed if the Finanzamt agrees on application in hardship cases.
- Freelancers in the legal sense (Freiberufler) need no trade registration. If your work counts as a trade (Gewerbe), you also register it with your municipality.
- Whether you are a Freiberufler depends on the type of work, not on what you would prefer (§ 18(1) no. 1 EStG).
- The income tax return is due seven months after the end of the year. For 2025 that was 31 July 2026.
Freiberufler or Gewerbe?
Settle this before you register, because trade registration and trade tax depend on it.
Under § 18(1) no. 1 EStG, Freiberufler are mainly:
- people doing scientific, artistic, literary, teaching or educational work
- the so-called listed professions (Katalogberufe), for example doctors, lawyers, tax advisers, engineers, architects, journalists, translators and interpreters
- professions similar to a listed one
A Gewerbe is, put simply, any other self-employed activity run for profit: trading, online shops, hospitality, crafts, brokering.
The line is not always clear. Consulting and coaching are often classed as Gewerbe, even if the work feels “intellectual”. For graphic and web design, it depends on whether the work counts as artistic. Software development can be engineering-like work, but doesn’t have to be.
The Finanzamt decides based on what you write in the questionnaire. If your work sits in a grey area, a short conversation with a tax adviser (Steuerberater) before you submit is worth it. They should look at your exact activity description, your training and your client structure.
Step 1: Gather what you need
For the questionnaire you need:
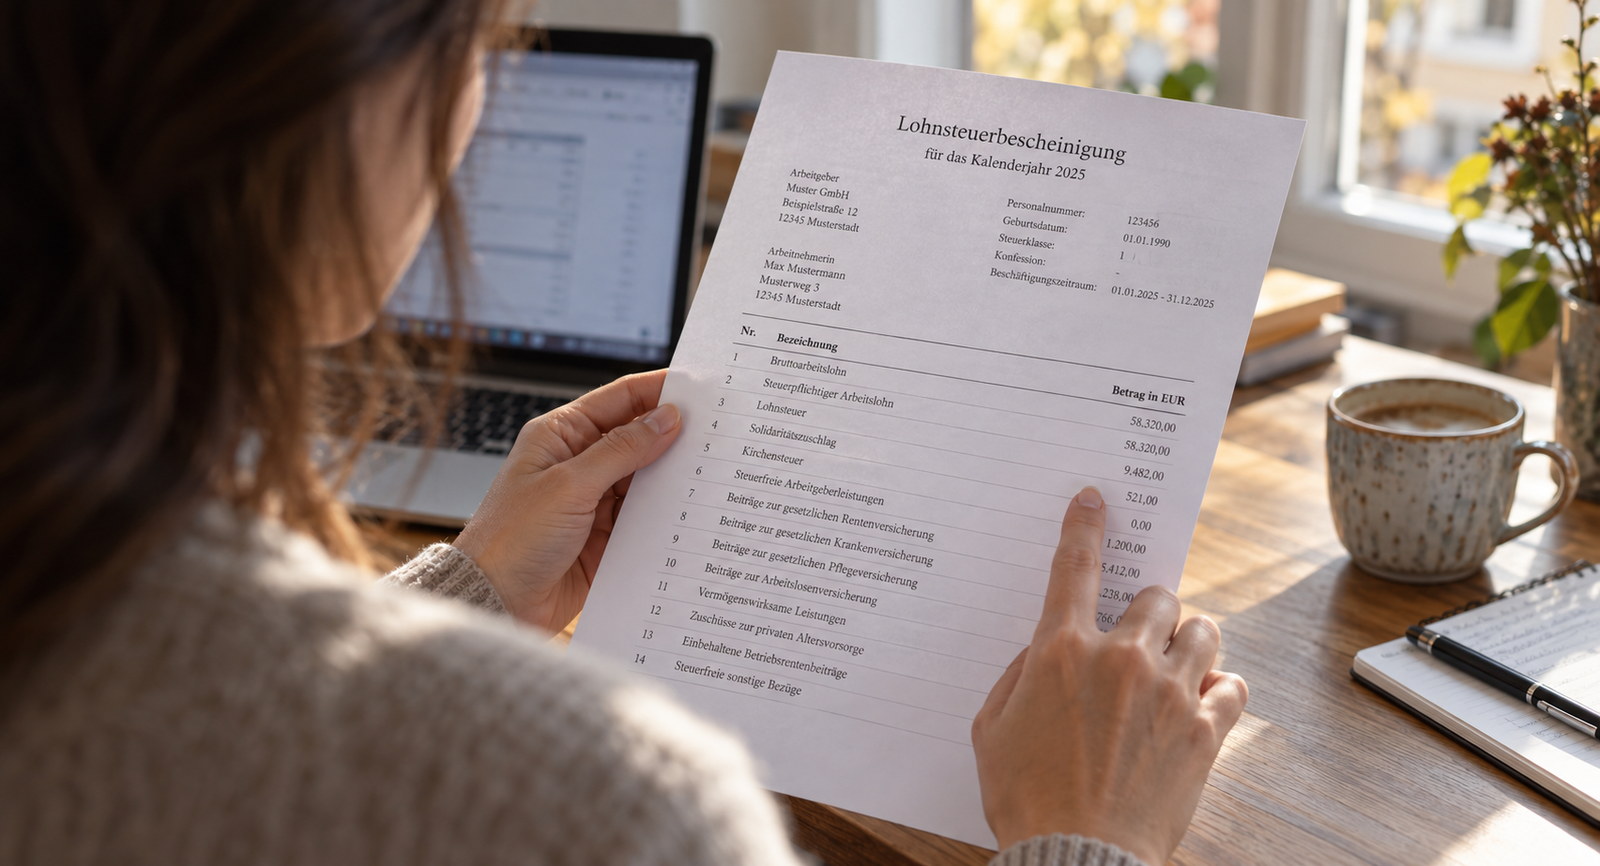
- your tax identification number (Steuer-Identifikationsnummer), found on your annual wage tax statement (Lohnsteuerbescheinigung) or on the letter from the Federal Central Tax Office
- your bank details
- a short description of your work
- an estimate of turnover and profit for the first and the following year (a realistic estimate is enough)
- your existing tax number (Steuernummer), if you have one
Step 2: Register with the Finanzamt
For Freiberufler
-
Set up an ELSTER account. If you don’t have one, register at elster.de. Part of the access details arrives by post, so start early.
- Fill in the tax registration questionnaire. Search for “Fragebogen zur steuerlichen Erfassung” in Mein ELSTER. It asks for:
- your activity and start date
- your expected turnover and profit
- whether you want to use the Kleinunternehmer scheme (small business VAT exemption)
- whether you want to calculate VAT on payments received (Ist-Versteuerung)
-
Submit it electronically. The questionnaire must go through ELSTER. Post or in person only works if the Finanzamt allows it on application, for example because using a computer is unreasonable for you.
- Wait for your Steuernummer. The Finanzamt sends it by post. You may work before it arrives. Invoices must show your Steuernummer or your VAT ID (USt-IdNr), so ideally issue them once the number is there.
For a Gewerbe
- Register the trade with your municipality. The trade office (Gewerbeamt) of your town is responsible. The municipality sets the fee.
- Still fill in the questionnaire. The municipality passes your trade registration on to the Finanzamt (§ 138(1) AO), but you still have to submit the tax registration questionnaire through ELSTER yourself, again within one month.
Step 3: Know your tax obligations
Income tax (Einkommensteuer)
- Every year you file an income tax return with the Anlage EÜR (the profit statement), both electronically.
- The deadline is seven months after year end (§ 149(2) AO). For tax year 2025 that was 31 July 2026. With a tax adviser, it runs to the end of February of the year after next; for 2025 that is 1 March 2027, because 28 February 2027 is a Sunday.
- The Finanzamt can set advance payments (Vorauszahlungen), due on 10 March, 10 June, 10 September and 10 December (§ 37 EStG). They are not optional: once you receive an advance payment notice, you pay. Put part of every payment you receive aside from the start.
VAT (Umsatzsteuer)
- If your turnover was at most 25,000 EUR last year and stays at most 100,000 EUR this year, you can use the Kleinunternehmer scheme (§ 19 UStG). In the year you start, only the 25,000 EUR limit applies, measured on the current year.
- Without the scheme, you charge VAT on your invoices and file VAT advance returns (Umsatzsteuer-Voranmeldungen), monthly or quarterly. Up to and including 2026, the expected tax decides which in your first year (§ 18(2) UStG).
Trade tax (Gewerbesteuer)
- Only applies to a Gewerbe, not to Freiberufler.
- The local multiplier (Hebesatz) depends on the municipality.
Step 4: Set up your routines
A separate account
- Sole traders are not legally required to have a business account. A dedicated account for all business payments still makes bookkeeping much easier, because bank transactions can be matched cleanly. That is practical advice, not a legal duty.
Bookkeeping
- Record income and expenses from day one.
- Keep invoices and receipts organised; accounting vouchers (Buchungsbelege) must be kept for eight years (§ 147(3) AO).
Invoices
- Your invoices must contain the mandatory details under § 14(4) UStG. Our guide to professional invoices lists them.
Common mistakes
Missing the one-month deadline. Register no later than a month after you start. Registering much later means reporting turnover and profit retroactively.
Not setting money aside for tax. The first income tax bill and the first advance payments often arrive together.
Mixing private and business payments. It’s allowed, but it makes every check tedious.
Not having deadlines in your calendar. VAT advance returns are due on the 10th of the following month; annual returns seven months after year end.
When a tax adviser is worth it
A Steuerberater makes sense if:
- it’s unclear whether your work is Freiberuf or Gewerbe
- you have clients abroad and need to apply the VAT rules for cross-border services
- you’re planning larger purchases and want to optimise depreciation
- you’re also employed and the two incomes interact
How Solobooks helps
With Solobooks you write invoices with all mandatory details, match payments against your bank account, and always see your turnover and profit so far. You submit VAT advance returns and the Anlage EÜR directly from Solobooks to ELSTER.
FAQ
When do I have to register with the Finanzamt? Within one month of starting your activity (§ 138(4) AO).
Can I submit the questionnaire on paper? Only if the Finanzamt allows it on application. The normal route is electronic submission through ELSTER.
Do I need a trade registration as a Freiberufler? No. Freiberufler only register with the Finanzamt. If your work is classed as a Gewerbe, you also need a trade registration.
Do I need a separate business bank account? Not by law as a sole trader. It is strongly recommended, though.
Can I work before my Steuernummer arrives? Yes. Your invoices should show your Steuernummer or VAT ID, so ideally issue them once you have the number.
Need help?
If you have questions about registration:
- Email us at support@solobooks.de
- Chat with us in the app
Sources
- § 138 AO – Anzeigen über die Erwerbstätigkeit
- § 149 AO – Abgabe der Steuererklärungen
- § 37 EStG – Einkommensteuer-Vorauszahlung
- § 18 EStG – Selbständige Arbeit
- § 19 UStG – Kleinunternehmer
- § 18 UStG – Besteuerungsverfahren
- § 147 AO – Aufbewahrung von Unterlagen
Last checked: 30 October 2026. This article is general information, not tax advice for your individual case. Legislation and official guidance change — the current version of each source prevails.
Last updated: October 30, 2026
Expert Tip
Set aside the calculated VAT in a separate account monthly. This way you avoid liquidity bottlenecks when paying the tax office.
— Solobooks Team