Who Must File a German Tax Return, and Who Should Anyway
There are two routes into a German income tax return, and they differ in almost everything: whether you have a choice, how long you have, and what happens if the date passes.
This guide places your case. It covers tax year 2025, the return you file in 2026.
The short version
- Pflichtveranlagung (mandatory assessment) means the tax office expects your return. The cases sit in § 46 EStG.
- Antragsveranlagung (assessment on application) means you file voluntarily, up to four years after the fact.
- For 2025 the mandatory deadline was 31 July 2026, or 1 March 2027 with a tax adviser or a Lohnsteuerhilfeverein.
- Voluntarily, you can still file the 2025 return until 31 December 2029.
- Wage replacement benefits over 410 euros and other income over 410 euros are the two most common triggers.
- Filing voluntarily, you can usually withdraw if the result would be a payment due. In a mandatory case you cannot.
When you have to file
The cases come from § 46 Abs. 2 EStG. The ones that matter in practice:
Wage replacement benefits over 410 euros. Unemployment benefit, short-time work allowance, sick pay, parental allowance, maternity pay, insolvency benefit. These are tax free, but they fall under Progressionsvorbehalt and so raise the rate applied to the rest of your income. This is by far the most common trigger.
Other income over 410 euros on which no wage tax was withheld: self-employed side work, letting property, pensions. Below 410 euros the Härteausgleich relief applies.
More than one employment at the same time, meaning wages from a second job taxed under Steuerklasse VI.
Certain tax class combinations for married couples: III and V, or IV with the Faktorverfahren. Plain IV and IV does not trigger it on its own.
A registered allowance as a wage tax deduction feature, for instance for high work-related expenses or a disability, where your salary also exceeded that year’s threshold. The child allowance and the flat allowances for disability and survivors do not trigger this.
A severance payment or pay for several years’ work taxed at the reduced rate under the Fünftelregelung.
Investment income with no tax withheld, for instance from a foreign broker where no Abgeltungsteuer was deducted.
A loss carryforward established in an earlier year.
Divorce and remarriage in the same year, for one of the people involved.
Pensioners are a separate case. The obligation there does not come from § 46 EStG but arises when the taxable portion of pension income exceeds the basic allowance, which for 2025 is 12,096 euros.
When filing voluntarily pays
Wage tax withheld over the year knows nothing about your individual deductions. It calculates as though every month were identical and as though you had only the standard allowance. Almost any departure from that produces a refund.
Typical cases:
- Work-related expenses over 1,230 euros. The standard allowance is deducted anyway; everything above it is extra money. Our guide to work-related expenses for employees covers what qualifies.
- You only worked part of the year, after studying, parental leave, or a gap between jobs. Withholding treats each month as though it continued all year, so it takes too much.
- You got married. The splitting tariff only takes full effect at assessment.
- High medical or care costs, once they exceed your reasonable burden threshold.
- Tradespeople and household services. These come off the tax itself rather than your income, and withholding knows nothing about them.
- Donations, church tax, childcare costs.
- A loss from side work that you want to offset against your salary.
The deadlines side by side
| Case | Deadline for tax year 2025 |
|---|---|
| Mandatory, filing yourself | 31 July 2026 |
| Mandatory, with a tax adviser or Lohnsteuerhilfeverein | 1 March 2027 |
| Voluntary | 31 December 2029 |
1 March 2027 arises because the statutory date at the end of February falls on a Sunday, so the deadline moves to the next working day.
Voluntary filing runs on a four-year clock from the end of the tax year:
| Tax year | Voluntary filing possible until |
|---|---|
| 2022 | 31 December 2026 |
| 2023 | 31 December 2027 |
| 2024 | 31 December 2028 |
| 2025 | 31 December 2029 |
So 2022 expires in a few months.
If you missed the mandatory deadline
File anyway. The tax office can impose a Verspätungszuschlag (late filing penalty) under § 152 AO, and its size depends partly on how long the return is outstanding. If nothing arrives, the office can estimate your tax base, and estimates rarely favour the taxpayer.
For voluntary filing the July date is irrelevant. There is no penalty and no estimate, because you were never obliged.
The difference most people miss
With an Antragsveranlagung you can usually still call it off. If it turns out the return would produce a payment due, you can object to the assessment and withdraw your application while the assessment is not yet final. The outcome is as though you had never filed.
With a Pflichtveranlagung there is no way back. You had to file, and the result stands.
Practically: if you are not obliged and you are unsure whether a refund is coming, the downside of filing voluntarily is small. Work it out, and file if the number suits.
What to do
- Work through the list above. One item is enough to make it mandatory.
- Find your certificates for wage replacement benefits. These amounts are not always on your payroll statement. Unemployment and parental allowance are certified separately.
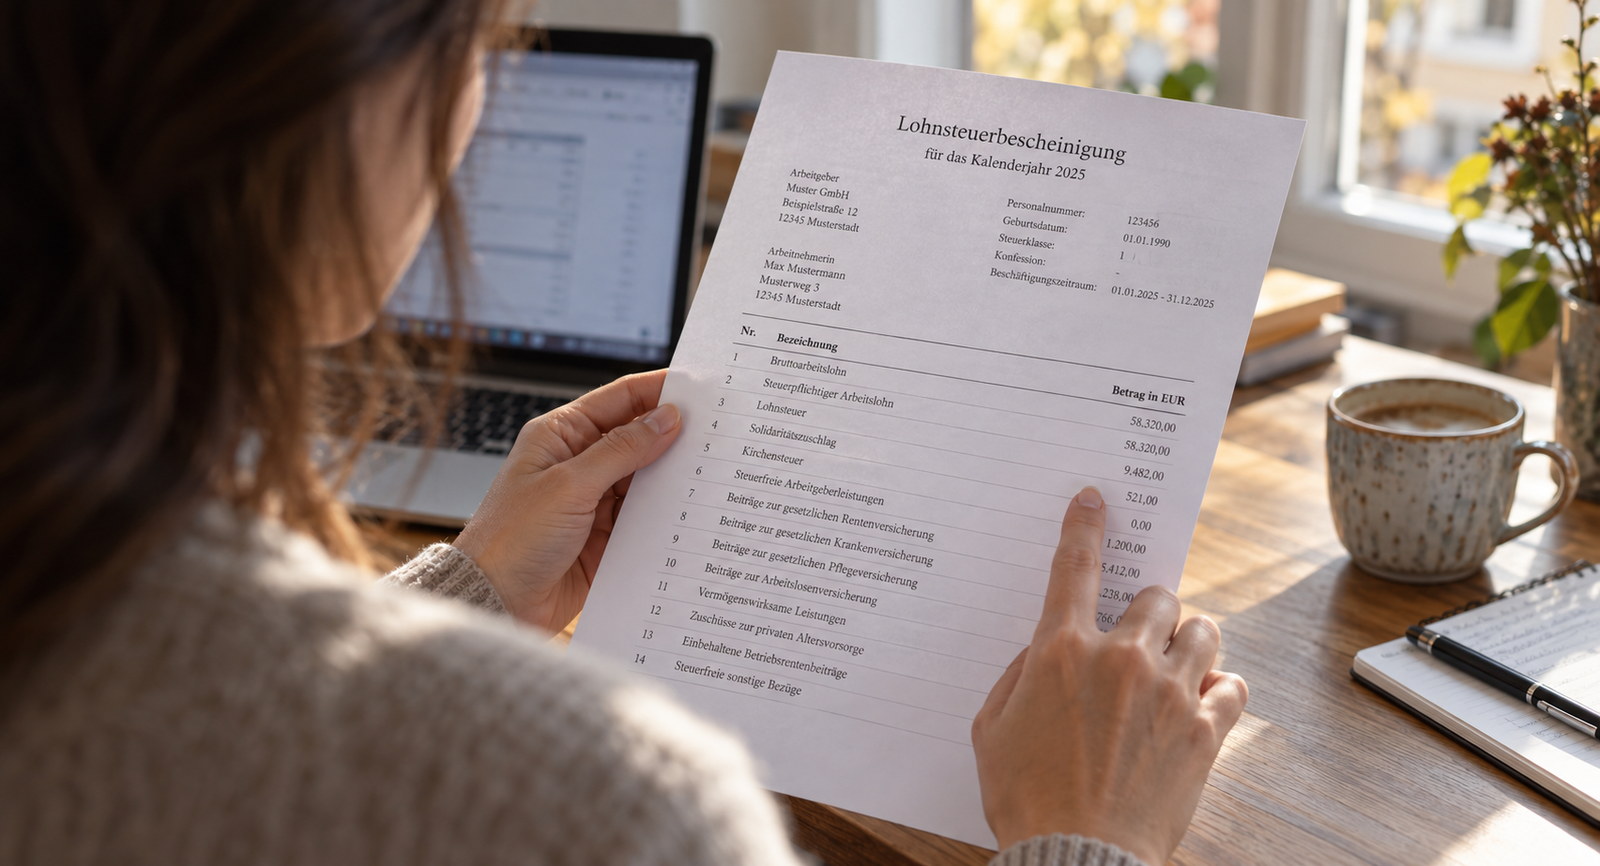
- Check every Lohnsteuerbescheinigung. Two for the same year often means mandatory filing. Our guide to reading your Lohnsteuerbescheinigung explains the fields.
- Calculate rather than guess. Working a return through takes less time than wondering whether it is worth it.
How Solobooks helps
Solobooks asks the questions that decide the obligation: wage replacement benefits, other employments, tax class, side income. The answers produce the full return without you having to know which case of § 46 EStG applies to you.
Your estimated refund is recalculated as you go and stays visible throughout, so anyone filing voluntarily can see before submitting whether it is worth it. You pay only on submission.
For the process end to end, see our step-by-step guide for employees.
Frequently asked questions
I received parental allowance in 2025. Do I have to file? If your wage replacement benefits totalled more than 410 euros, yes. Parental allowance is almost always above that.
Is the 410 euros per benefit or in total? In total. All benefits subject to Progressionsvorbehalt in that year are added together.
I had a mini-job alongside my main job. Is that tax class VI? A mini-job taxed at the flat rate is not. If the second job is taxed under Steuerklasse VI, the obligation arises.
What is the Härteausgleich? Where side income with no wage tax withheld is 410 euros or less, it stays untaxed. Between 410 and 820 euros only part of it is brought into account.
We are married and both on tax class IV. Do we have to file? Not for that reason alone. Only the Faktorverfahren or the III and V combination triggers it.
Can I file voluntarily even though I was actually obliged? Then it is not voluntary. It remains a late mandatory filing, with the consequences under § 152 AO.
Sources
- § 46 EStG, assessment where income from employment is received
- § 32b EStG, Progressionsvorbehalt
- § 149 AO, filing of tax returns, and § 108 AO on calculating deadlines
- § 152 AO, late filing penalty
- § 169 AO, assessment period
- Finanzministerium Rheinland-Pfalz, table of tax return filing deadlines
Last checked: 17 September 2026. This article is general information, not tax advice for your individual case. Legislation and official guidance change, the current version of each source prevails.
Last updated: September 13, 2026
Expert Tip
If you were not required to file, your 2025 deadline runs to 31 December 2029. For 2022 it expires on 31 December 2026.
— Solobooks Team